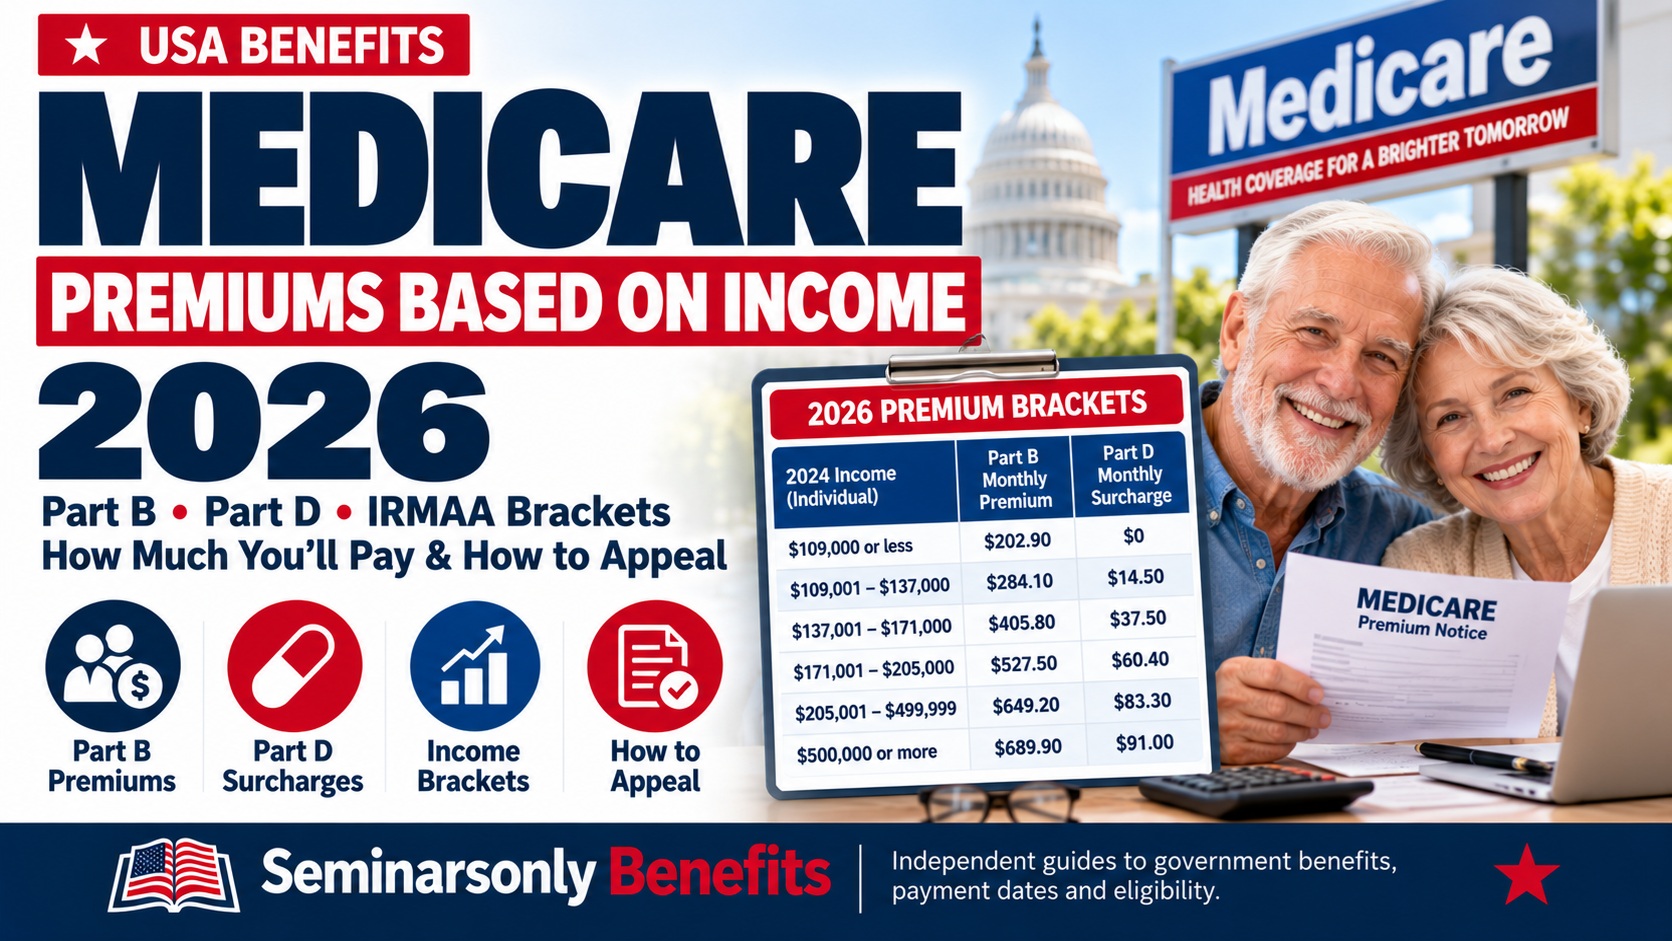
Medicare Premiums Based on Income 2026: Part B and Part D IRMAA Chart
Quick Answer: How Much Are Medicare Premiums Based on Income in 2026?
- Standard Part B premium: $202.90 monthly.
- Higher-income Part B premium: $284.10 to $689.90 monthly.
- Income threshold: Above $109,000 for individual filers or $218,000 for married couples filing jointly.
- Income year used: Generally 2024 tax return information.
- Part D surcharge: $14.50 to $91.00 monthly for higher-income beneficiaries, in addition to the drug plan premium.
- Appeal option: You may request a new IRMAA determination after certain life-changing events, such as retirement or reduced work hours.
Medicare premiums are not the same for everyone. While most beneficiaries pay the standard Medicare Part B premium, people with higher incomes may pay an additional charge called the Income-Related Monthly Adjustment Amount (IRMAA).
In 2026, the standard Medicare Part B premium is $202.90 per month. Depending on income and tax filing status, the monthly Part B premium can increase to $689.90.
Higher-income beneficiaries may also pay a separate IRMAA surcharge for Medicare Part D prescription drug coverage.
This guide explains the official 2026 income brackets, how Social Security calculates IRMAA, why 2024 income matters, how Medicare Advantage fits into the calculation and what to do if your income has dropped.
Medicare Part B Premiums Based on Income: 2026 Chart
The Social Security Administration generally determines 2026 Medicare income adjustments using modified adjusted gross income from 2024.
The following table applies to individuals filing single returns and married couples filing jointly. Other filing statuses may have different rules.
| 2024 Income: Individual | 2024 Income: Married Filing Jointly | 2026 Part B Premium Per Person, Monthly |
|---|---|---|
| $109,000 or less | $218,000 or less | $202.90 |
| Above $109,000–$137,000 | Above $218,000–$274,000 | $284.10 |
| Above $137,000–$171,000 | Above $274,000–$342,000 | $405.80 |
| Above $171,000–$205,000 | Above $342,000–$410,000 | $527.50 |
| Above $205,000–below $500,000 | Above $410,000–below $750,000 | $649.20 |
| $500,000 or more | $750,000 or more | $689.90 |
These figures are monthly amounts for each Medicare beneficiary, not combined household premiums.
If both spouses are enrolled in Part B, each generally pays the applicable individual premium based on the couple’s joint income bracket.
Official source: Social Security Administration — Medicare Premiums.
What Income Triggers Higher Medicare Premiums in 2026?
For an individual filing a single return, the first IRMAA bracket begins when modified adjusted gross income exceeds $109,000.
For married couples filing jointly, it begins when combined modified adjusted gross income exceeds $218,000.
At the first higher-income bracket, the monthly Part B premium rises from $202.90 to $284.10.
This is an increase of $81.20 per month, or $974.40 over twelve months, for each affected beneficiary.
What Is Medicare IRMAA?
IRMAA stands for Income-Related Monthly Adjustment Amount.
It is an additional premium charge for certain Medicare beneficiaries whose income exceeds federal thresholds.
IRMAA can apply to:
- Medicare Part B: Medical insurance covering qualifying physician services, outpatient care and other services.
- Medicare Part D: Prescription drug coverage, including eligible beneficiaries enrolled in Medicare Advantage plans with drug coverage.
IRMAA does not mean Medicare has changed your underlying eligibility for coverage. It changes the amount you must pay for qualifying coverage.
The Social Security Administration generally determines the income-related adjustment, while Medicare administers the relevant coverage.
Medicare Part D IRMAA Premiums for 2026
Medicare Part D premiums vary by prescription drug plan. Higher-income beneficiaries pay an additional federal surcharge on top of their plan premium.
Here are the official 2026 Part D IRMAA amounts.
| 2024 Individual Income | 2024 Joint Income | 2026 Monthly Part D IRMAA |
|---|---|---|
| $109,000 or less | $218,000 or less | $0 |
| Above $109,000–$137,000 | Above $218,000–$274,000 | $14.50 |
| Above $137,000–$171,000 | Above $274,000–$342,000 | $37.50 |
| Above $171,000–$205,000 | Above $342,000–$410,000 | $60.40 |
| Above $205,000–below $500,000 | Above $410,000–below $750,000 | $83.30 |
| $500,000 or more | $750,000 or more | $91.00 |
Important: The figures above are surcharges, not the full monthly Part D premium.
For example, if your prescription drug plan costs $40 monthly and your IRMAA surcharge is $37.50, your combined monthly Part D premium obligation would be $77.50.
IRMAA is generally collected by Social Security or Medicare rather than paid directly to your Part D insurance plan.
How Does Medicare Calculate Income for 2026?
Medicare uses a specific measure called modified adjusted gross income (MAGI).
For IRMAA purposes, MAGI generally equals:
Adjusted gross income is generally found on line 11 of IRS Form 1040, while tax-exempt interest is reported on line 2a.
This means Medicare does not simply use the amount of money deposited into your bank account each month.
Does Social Security Count Toward Medicare IRMAA Income?
Taxable Social Security benefits included in adjusted gross income can affect the MAGI calculation.
However, Medicare does not simply add every dollar of Social Security benefits to MAGI regardless of tax treatment.
Other income sources that may affect AGI include:
- Wages and self-employment earnings.
- Taxable pension distributions.
- Taxable traditional IRA withdrawals.
- Capital gains.
- Interest and dividend income.
- Taxable portions of Social Security benefits.
Tax-exempt interest is added separately when calculating IRMAA MAGI.
Do Roth IRA Withdrawals Increase IRMAA?
Qualified Roth IRA distributions generally are not included in adjusted gross income, so they ordinarily do not increase IRMAA MAGI.
However, nonqualified distributions may have different tax consequences. Your specific tax circumstances determine the treatment.
Can Capital Gains Increase Medicare Premiums?
Yes. A large taxable capital gain may increase AGI and move a beneficiary into a higher IRMAA bracket.
For example, selling an appreciated investment or property may produce a one-time income increase that affects Medicare premiums two years later.
Not every sale produces taxable income, and exclusions or deductions may apply. Review your actual federal tax return rather than assuming the sale price is fully counted.
Why Does Medicare Use Income From Two Years Ago?
Social Security generally uses the most recent tax information available from the Internal Revenue Service.
Because current-year tax returns are not yet available when premiums are established, the agency usually looks back two years.
| Medicare Premium Year | Tax Year Generally Used |
|---|---|
| 2025 | 2023 |
| 2026 | 2024 |
| 2027 | Generally 2025 |
If the usual tax-year information is unavailable, Social Security may use other available IRS information under its rules.
For this reason, the income on your 2026 paychecks does not automatically determine your 2026 IRMAA bracket.
Medicare IRMAA 2026 for Married Filing Separately
Married beneficiaries who file separate federal tax returns may face a different premium calculation if they lived with their spouse at any time during the tax year.
For this filing category, the published 2026 Part B premium brackets are:
| 2024 MAGI | 2026 Monthly Part B Premium |
|---|---|
| $109,000 or less | $202.90 |
| Above $109,000 but below $394,000 | $649.20 |
| $394,000 or more | $689.90 |
The corresponding Part D IRMAA surcharges for the higher two brackets are generally $83.30 and $91.00 monthly, respectively.
Different rules may apply when married spouses lived apart for the entire tax year.
Always review the specific filing-status category on your Social Security IRMAA notice.
Medicare Premium Examples for Different Income Levels
Example 1: Single Retiree With $75,000 Income
A single Medicare beneficiary has 2024 IRMAA MAGI of $75,000.
Because this is below the $109,000 threshold, the beneficiary generally pays the standard 2026 Part B premium of $202.90 monthly.
No income-related Part D surcharge applies.
Example 2: Single Retiree With $125,000 Income
A single beneficiary has 2024 MAGI of $125,000.
This falls into the first higher-income bracket.
- Part B premium: $284.10 monthly.
- Part D IRMAA: $14.50 monthly.
- Combined Part B and Part D IRMAA-related obligation: $298.60 monthly, before the actual Part D plan premium.
Over twelve months, the Part B premium alone totals $3,409.20.
Example 3: Married Couple With $300,000 Joint Income
A married couple files jointly and reports $300,000 in 2024 MAGI.
Their income falls into the bracket above $274,000 and up to $342,000.
Each spouse enrolled in Part B generally pays $405.80 monthly.
If both have Part D coverage, each also owes the applicable $37.50 monthly Part D IRMAA surcharge, in addition to their plan premiums.
The combined Part B premiums for both spouses would total $811.60 monthly.
Example 4: Income Fell After Retirement
Suppose a beneficiary earned $180,000 in 2024 but retired in 2025 and now receives much less income.
The 2026 premium may initially reflect the higher 2024 income.
However, retirement is a qualifying life-changing event that may allow the beneficiary to request a new IRMAA determination using more recent income information.
The Social Security Administration reviews the request and supporting evidence before deciding whether to adjust the premium.
How to Appeal Medicare IRMAA in 2026
If you believe your income-based Medicare premium is incorrect, you may be able to request a review.
There are different procedures depending on whether the issue is an incorrect tax record, an administrative error or a qualifying life-changing event.
Step 1: Review Your IRMAA Notice
Check the tax year, filing status and MAGI used by Social Security.
Compare those figures with your federal income tax return and any IRS corrections.
Step 2: Determine Whether You Had a Qualifying Life-Changing Event
Examples recognized by Social Security include:
- Marriage.
- Divorce or annulment.
- Death of a spouse.
- Work stoppage, including retirement.
- Work reduction.
- Loss of income-producing property under qualifying circumstances.
- Loss of certain pension income.
- Employer settlement payment under qualifying circumstances.
Not every income reduction qualifies. For example, ordinary investment losses or voluntary withdrawals do not automatically establish a qualifying life-changing event.
Step 3: Complete Form SSA-44 When Applicable
Social Security provides Form SSA-44, Medicare Income-Related Monthly Adjustment Amount — Life-Changing Event.
The form asks about the event, its date and your expected income.
Depending on the circumstances, you may need to provide supporting documents such as retirement records or income information.
Request a Lower Medicare IRMAA
Step 4: Submit the Request to Social Security
Follow Social Security’s current submission instructions. You can contact the agency for assistance with your particular circumstances.
Keep copies of the form and supporting evidence.
Step 5: Review the Decision
Social Security will determine whether a new IRMAA calculation is appropriate.
If the agency does not grant your request, your notice should explain the applicable appeal or reconsideration options.
Be mindful of deadlines listed in the notice.
Does Medicare Advantage Have an Income-Based Premium?
Medicare Advantage, also called Part C, is offered through private insurance companies approved by Medicare.
Most people enrolled in Medicare Advantage must continue paying their Medicare Part B premium.
Therefore, a beneficiary subject to Part B IRMAA generally remains responsible for the higher Part B amount even when enrolled in a Medicare Advantage plan.
Medicare Advantage plans may also charge their own plan premiums.
If a Medicare Advantage plan includes Part D prescription drug coverage, the beneficiary may also owe Part D IRMAA when applicable.
A plan advertised as having a $0 additional monthly premium does not necessarily eliminate the standard Part B premium or any applicable IRMAA.
Is Medicare Part A Premium Based on Income?
Medicare Part A is different from Parts B and D.
Most people qualify for premium-free Part A based on their own or a spouse’s Medicare-covered work history.
People who do not qualify for premium-free Part A may need to pay a Part A premium.
The amount is generally determined by qualifying work credits rather than the Part B and Part D IRMAA income brackets.
CMS reports that approximately 99% of Medicare beneficiaries do not pay a Part A premium.
How Much Is the Medicare Part B Deductible in 2026?
The standard Medicare Part B annual deductible for 2026 is $283.
This is separate from the monthly premium.
Under Original Medicare, beneficiaries generally pay the annual deductible before Medicare begins paying its share of many covered Part B services.
After the deductible, a beneficiary typically pays 20% coinsurance for many Medicare-covered services, although exceptions and other coverage arrangements may apply.
Paying IRMAA does not mean that the Part B deductible automatically becomes higher.
Can Low-Income Beneficiaries Get Help Paying Medicare Premiums?
Yes. Medicare Savings Programs can help eligible beneficiaries with certain Medicare costs.
The four principal programs are:
- QMB: Helps with Part A and Part B premiums and Medicare-covered cost sharing.
- SLMB: Helps pay Part B premiums.
- QI: Helps pay Part B premiums for eligible applicants.
- QDWI: Helps certain working people with disabilities pay Part A premiums.
These programs have separate income and resource eligibility requirements, and state rules can be more generous than federal reference limits.
For the complete 2026 eligibility tables, see our Medicare Savings Programs 2026 Guide.
People with limited income and resources may also qualify for Medicare Extra Help with prescription drug costs.
How to Check Your Medicare Premium for 2026
- Review your Social Security or Medicare premium notice.
- Identify whether you pay the standard Part B premium or an IRMAA-adjusted amount.
- Check the tax filing status and income year used.
- Compare the amount with the official 2026 bracket table.
- Review any separate Part D IRMAA charge.
- Contact Social Security if the income information or determination appears incorrect.
If your premiums are deducted from Social Security benefits, your payment statement can also help you identify the deduction.
Important Medicare Premium Tips for 2026
- Remember that 2026 IRMAA is generally based on 2024 income.
- Check both Part B and Part D surcharges.
- Use MAGI rather than gross salary alone.
- Review large taxable capital gains and retirement distributions when estimating future IRMAA.
- Ask Social Security about a new determination after qualifying life-changing events.
- Do not assume a $0-premium Medicare Advantage plan eliminates Part B costs.
- Explore Medicare Savings Programs if you have limited income and resources.
- Use official Medicare and SSA notices to confirm your actual premium.
Official Medicare, CMS and SSA References
- SSA — Monthly Medicare Premiums for 2026
- CMS — 2026 Medicare Part B Premiums, Deductibles and Part D IRMAA
- Medicare.gov — What Medicare Costs
- SSA — Request a Lower Income-Related Medicare Premium
- SSA — IRMAA Modified Adjusted Gross Income Rules
- Medicare.gov — Medicare Savings Programs
Editorial review: Income thresholds, Part B premiums, Part D surcharges and MAGI rules were reviewed against official CMS, SSA and Medicare publications on October 28, 2026.
More Guides From Seminarsonly Benefits
- Medicare Savings Programs 2026: Income and Resource Limits
- LIHEAP Heating Assistance 2026–2027
- WIC Income Guidelines 2026–2027
- USA Government Benefits
Learn about our fact-checking standards in the Editorial Policy or request a correction through our Corrections Policy.
TL;DR — Medicare Premiums Based on Income 2026
- Standard Part B premium: $202.90 monthly.
- Income-based Part B premiums range from $284.10 to $689.90 monthly.
- Individual IRMAA threshold: income above $109,000.
- Married filing jointly IRMAA threshold: income above $218,000.
- 2026 premiums generally use 2024 tax return information.
- Part D IRMAA surcharges range from $14.50 to $91.00 monthly.
- IRMAA MAGI generally equals adjusted gross income plus tax-exempt interest.
- Married filing separately has special brackets.
- Qualifying life-changing events may allow a lower IRMAA determination.
- Medicare Savings Programs may help eligible lower-income beneficiaries pay Medicare costs.